The Second Trip Is Where the Margin Disappears
Why repeat visits and rework quietly consume trade-contractor profit—and how to find the operating constraint behind them.
The first trip earns the revenue.
The second trip often consumes the margin.
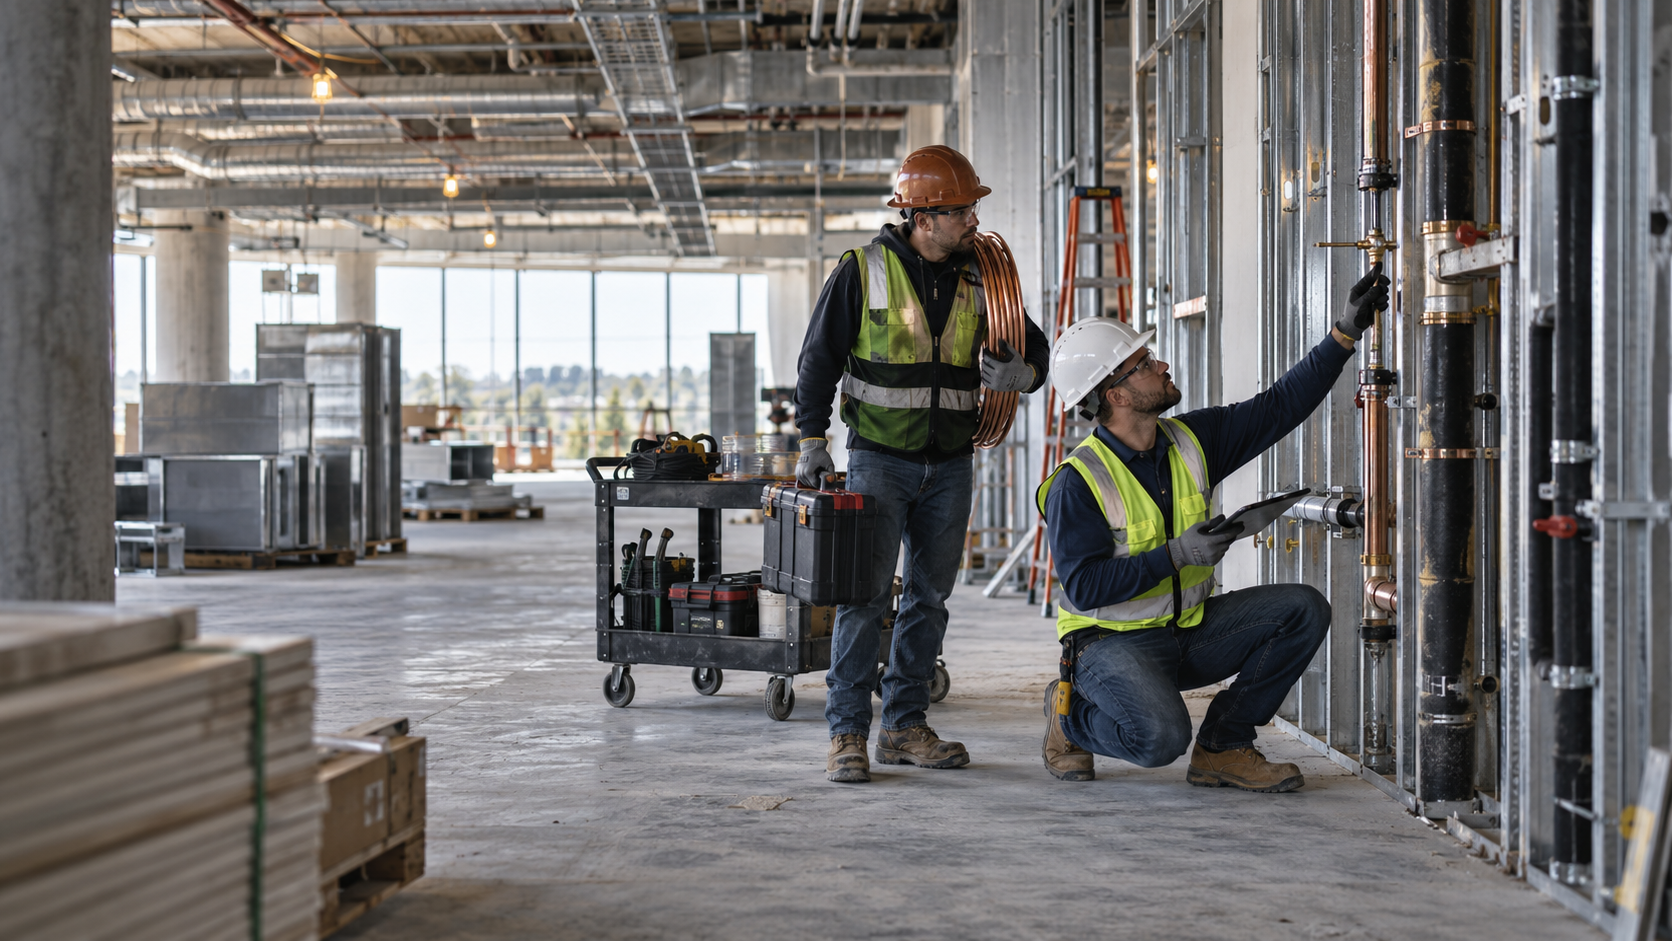
For many trade contractors, returning to a jobsite is treated as a routine field issue: a technician goes back, a repair is made, the punch item is closed, and the schedule moves forward. The event may never appear as a distinct loss on the income statement. Its labor is absorbed into payroll. Fuel remains inside vehicle expense. Replacement material is charged to the project or overhead. A supervisor makes another call. A coordinator changes the schedule.
The company sees activity.
What it may not see is the margin that disappeared.
A return visit can combine several losses at once:
- Nonbillable labor to complete or correct previously performed work
- Travel time, fuel, vehicle expense, and remobilization
- Replacement materials and damaged components
- Supervisor, coordinator, and project-manager intervention
- Schedule disruption for other crews and customers
- Delayed completion documentation, billing, or retainage release
- Capacity displaced from new, revenue-producing work
The visible repair is therefore only part of the economic effect. The operating question is not simply, “How much did the repair cost?” It is:
What recurring condition is forcing the business to consume capacity more than once for the same unit of revenue?
Rework is measurable—but frequently underreported
The reported cost of construction rework varies widely because companies do not use a common definition or capture the same cost components.
A 2026 technical note from the American Society of Civil Engineers summarized research based on actual contractor data. It found that recorded precompletion field-rework costs averaged 0.38% of contract value, with results ranging from 0.01% to 3.67%. When estimated postcompletion corrections were included, the average increased to 0.76%, with a range of 0.02% to 7.34%.
The more revealing finding was not the average. Actual rework costs had been underreported by 300%.
That matters because even a seemingly small percentage can consume a meaningful share of contractor profit. A company targeting an 8% operating-profit margin and losing 0.76% of revenue to rework would surrender the equivalent of 9.5% of its planned operating profit:
At the upper end of the study’s reported range, the effect would be far more severe. But the purpose of the benchmark is not to apply one percentage to every contractor. The study itself was exploratory, and trade mix, accounting practices, project type, contractual recovery, and the definition of rework all affect the result.
Rework cannot be controlled if the company does not distinguish it from normal production.
Why repeat visits become invisible
Most job-cost systems are designed to determine whether a project or work order stayed within budget. They are not always designed to explain why the same scope consumed multiple mobilizations.
A crew may return because:
- The preceding trade was incomplete
- The site was not accessible or ready
- Approved information was missing or changed
- Required material was unavailable
- The original scope was unclear
- The first installation failed inspection or internal quality review
- Another party damaged completed work
- The crew was released before all completion conditions were verified
Those causes have different owners and require different countermeasures. When every event is labeled “callback,” “punch,” or “warranty,” leadership receives a count but not a diagnosis.
The company may then respond by telling crews to work faster, adding quality inspections, hiring more people, or increasing supervision. Each response adds cost. None necessarily addresses the governing constraint.
If most return visits are caused by incomplete work fronts, additional technician training will not solve the problem. If the failure occurs because approved scopes change after installation, a stricter field checklist may only document the same failure more efficiently. If material kits are incomplete, increasing crew capacity can create more waiting and more partially completed jobs.
The point of measurement is not to assign blame.
It is to locate the operating condition that repeatedly converts productive capacity into recovery work.
An illustrative margin-leakage example
Consider a specialty trade contractor completing 100 jobs in one month. The following example is illustrative and does not represent a GreanSea client result.
| Operating measure | Illustrative assumption |
|---|---|
| Completed jobs | 100 |
| Average revenue per job | $2,500 |
| Monthly revenue | $250,000 |
| Planned gross margin | 18% |
| Planned gross profit | $45,000 |
| Jobs requiring a nonbillable return visit | 12 |
| Repeat-visit rate | 12% |
Assume each return requires two technicians for three hours, plus travel, materials, and coordination:
| Direct cost per return visit | Calculation | Cost |
|---|---|---|
| Loaded field labor | 2 technicians × 3 hours × $45 | $270.00 |
| Vehicle, fuel, and travel burden | Illustrative allowance | $60.00 |
| Replacement or supplemental materials | Illustrative allowance | $75.00 |
| Coordination and supervision | 0.5 hour × $55 | $27.50 |
| Direct cost per return | $432.50 |
Across 12 return visits, direct monthly leakage equals $5,190.
| Margin effect | Amount |
|---|---|
| Planned gross profit | $45,000 |
| Direct repeat-visit cost | ($5,190) |
| Adjusted gross profit | $39,810 |
| Adjusted gross margin | 15.9% |
| Gross-margin reduction | 2.1 percentage points |
| Share of planned gross profit consumed | 11.5% |
If the pattern continued for 12 months, the direct cost would annualize to $62,280.
That figure still excludes potential lost contribution from displaced work. The 12 returns consume 72 technician-hours, equivalent to 4.5 two-person crew-days. If the company has sufficient backlog and could have deployed that capacity profitably, the economic effect may be larger. If demand is insufficient, that opportunity should not be counted.
This distinction matters. Credible margin analysis separates recorded cost, estimated cost, and conditional opportunity rather than combining them into one inflated claim.
The constraint may sit before the trade arrives
Rework is often discussed as a workmanship problem. Sometimes it is. But the defect or incomplete task can also be the downstream symptom of a release problem.
A trade may be dispatched before the site meets the conditions required for first-time completion. Drawings may not be final. Selections may be missing. Preceding work may be incomplete. Material may be on site but not verified. Access may be restricted. The crew arrives because the schedule says the activity should start—not because the work front is actually ready.
Once this happens, the trade faces a damaging choice:
- Leave without performing work and absorb a dry run.
- Complete the available portion and schedule a return.
- Improvise around the missing condition and accept quality risk.
All three choices can reduce margin.
The governing constraint may therefore be the organization’s release rule: the method used to decide whether work is ready to enter production.
A focused GreanSea sample
GreanSea would not begin by launching a broad quality program. A focused diagnostic would start with a small, evidence-based sample designed to determine where repeat visits originate.
1. Establish the baseline
Review 100 recently completed jobs or work orders from one value stream and one location. For each job, capture:
- Number of site visits
- Planned and actual labor hours
- Return-visit reason
- Direct labor, material, travel, and supervision cost
- Completion and invoice dates
- Whether the cause was internal, external, shared, or inconclusive
The initial measures would include first-time-complete rate, repeat-visit rate, average cost per return, technician-hours consumed, and days from first mobilization to invoice-ready completion.
2. Separate symptoms from causes
Code each return into a controlled cause structure—for example:
- Work-front readiness
- Scope or information error
- Material or equipment availability
- Workmanship or installation defect
- Damage after completion
- Access or customer condition
- Change initiated after release
- Cause not established
A Pareto analysis can then show whether one or two cause families account for most of the lost capacity.
3. Test the leading constraint
Suppose seven of the 12 returns in the illustrative sample trace to incomplete work-front readiness. GreanSea would test whether those jobs were released without verified prerequisites rather than assuming the crews were the problem.
The evidence might include dispatch records, photos, inspection status, missing-material logs, preceding-trade completion, scope revisions, and interviews with the dispatcher, supervisor, and field crew.
The conclusion would remain a hypothesis until competing explanations were tested.
4. Install a narrow countermeasure
If the release rule is confirmed as the constraint, the countermeasure could be a 24-hour readiness gate requiring evidence of:
- Approved scope and current information
- Required materials and equipment
- Completion of predecessor work
- Site access and customer readiness
- Photos or verification appropriate to the trade
- A named owner for unresolved exceptions
The gate should not become another administrative checklist. It should prevent scarce trade capacity from being released into work that cannot be completed.
5. Run a controlled pilot
Test the readiness gate on the next 25 comparable jobs. Compare the pilot with the baseline using the same definitions.
If the repeat-visit count fell from the equivalent of 12 per 100 jobs to six, the illustrative direct benefit would be:
- $2,595 in monthly direct cost avoided
- 36 technician-hours recovered
- 2.25 two-person crew-days returned to productive capacity
- Approximately $31,140 in annualized direct cost avoided if sustained
Those numbers would not be presented as realized savings until the company verified them over an agreed measurement period. A 25-job pilot can support an operating decision; it is not proof that the result will persist across every crew, location, or project type.
The right measures change the conversation
Leaders frequently track callbacks, punch items, warranty claims, and inspection failures. Those measures describe volume. They do not always describe economic consequence or control.
A stronger operating view connects five measures:
- First-time-complete rate: What percentage of work is completed without a nonbillable return?
- Repeat-visit burden: How many additional mobilizations and technician-hours are consumed?
- Cost per return: What labor, travel, material, and management expense is incurred?
- Cause concentration: Which verified cause family accounts for the largest share?
- Recovered capacity: When returns decline, is the released capacity converted into throughput, lower overtime, faster completion, or another measurable result?
The fifth measure prevents an important mistake. Time saved is not automatically cash realized. Recovered capacity creates financial value only when it is productively redeployed or when cost is actually removed.
Margin improvement begins with first-time completion
Trade contractors do not need every job to be perfect before they can improve margin. They need to know which repeat condition is consuming the most scarce capacity and why it continues to recur.
The second trip is rarely just a second trip.
It is another mobilization, another block of payroll, another interruption, another scheduling decision, and another delay between performing work and converting it into cash. When repeated across crews and projects, it becomes an operating model that quietly transfers profit into recovery activity.
The solution is not to eliminate every defect at once.
It is to make repeat work visible, quantify its economic effect, identify the governing cause, and protect the operation from releasing work that cannot be completed correctly the first time.
That is where margin recovery begins.
The financial scenarios in this article are illustrative and do not represent a guaranteed outcome or the result of a specific client engagement. Actual costs and recoverable value depend on the contractor’s trade, labor structure, accounting definitions, project mix, demand, evidence quality, management decisions, and implementation performance.